Will Customers Pay $2-3k for the Apple iPhone Duo / How Apple Wins by not being the Innovator, rather a Fast Follower / Super Proud Dad
Super Proud Dad
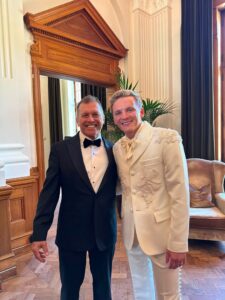
I am proud to share that my middle son, Cal, got married in Sweden this past July. It was a spectacular experience. Cal was featured in Vogue magazine for having his tuxedo made from his late mother’s wedding dress.
Amazing Best Man Toast
When I tell people I am not the best speaker in my own family, they think I am kidding. Check out my oldest son, Johnni’s two-minute speech.
How Apple Continues to Make Price Irrelevant
Apple’s foldable, the iPhone Duo, launched at $1,999 for the base 256GB model, climbing to around $3,000 for the fully loaded 2TB version. Pre-orders opened on October 16, with the phone officially out on October 23.
Counterpoint Research expects Apple to sell about 6 million iPhone Duo units in 2026, calling the pricing “a pretty bold move” for a first-generation foldable. Strong demand is expected, especially from existing iPhone Pro owners and early adopters who’ve been waiting specifically for an Apple foldable.
For context on where that sits in the market: the Duo is priced above Samsung’s Galaxy Z Fold6 (~$1,900) and Google’s Pixel 9 Pro Fold (~$1,800), and nearly double Apple’s own iPhone 18 Pro Max ($1,299) — so it’s unambiguously a premium, enthusiast-tier purchase, not a mainstream upgrade.
It’s not a phone most consumers will buy, but Apple doesn’t need “most consumers” — they need the segment that already spends $1,200+ on a Pro Max and wants the newest form factor. Early signs suggest that the segment is sizable enough to move several million units despite the price; a meaningful number of people will pay $2,000+, even if it remains a minority of the overall iPhone buyer base.
Apple isn’t trying to be first — it’s trying to be “right.”
Apple’s playbook has consistently been: let competitors ship an immature version of a category, let the market and the tech mature, then enter with a more polished, more integrated version. The iPod wasn’t the first MP3 player. The iPhone wasn’t the first smartphone. The iPad wasn’t the first tablet. AirPods weren’t the first wireless earbuds. Apple Watch wasn’t the first smartwatch. In each case, competitors had already done the work of proving demand and educating the market — Apple then swept in with a more refined experience.
Vertical integration lets them control the whole stack.
Because Apple controls hardware, silicon (their own chips now), OS, and software ecosystem end-to-end, they can make the pieces work together in ways competitors assembling from third-party components can’t easily match. A late entry with tighter integration often feels more finished than an earlier one cobbled together from off-the-shelf parts.
The ecosystem is the actual product.
Once someone owns an iPhone, the switching cost to leave isn’t really about any single device — it’s iMessage, AirDrop, Handoff, iCloud, Find My, shared subscriptions, Apple Watch pairing, HomeKit, etc. A new Apple product doesn’t have to be better than the competition in isolation; it just has to be better within an ecosystem someone is already locked into. That’s a moat competitors entering fresh don’t have.
Brand trust lowers the risk of buying “late.”
Customers who wait for the Apple version aren’t being irrational — Apple has built a reputation for shipping fewer bugs, better build quality, and longer software support than most competitors’ first-generation products. Being late is actually part of the value proposition: “we waited so you don’t have to be the beta tester.”
Marketing and retail execution outclass most competitors.
Apple’s launches, store experience, and marketing narrative consistently outperform functionally similar competitor products. A lot of perceived “ownership” of a category is about mindshare and cultural narrative, not just specs or timing.
Where this strategy has real limits
It’s slower and riskier in fast-moving categories. Apple has visibly struggled with this in generative AI — Siri and Apple Intelligence have lagged well behind OpenAI, Google, and others, and “wait and refine” hasn’t worked the same way there, partly because AI’s value is tied to model quality and iteration speed rather than hardware/ecosystem integration. So the pattern that’s worked for two decades in hardware categories isn’t a guarantee it’ll keep working in every domain going forward.
Overall global smartphone market: ~20-25%
Apple led 2025 with a 20% global share, the largest among the top five brands. Counterpoint Research projects Apple will hit a record ~25% share by the end of 2026 — its highest-ever level — as iPhone shipments stay roughly flat while most other manufacturers see double-digit declines due to rising memory/component costs. In Q2 2026 specifically, Apple’s share hit 21%, though Samsung briefly reclaimed the overall #1 spot in some quarters with 23%.
Premium segment (phones $600+): 65%
This is where Apple really dominates. For smartphones selling above $600, Apple owns 65% of the market, growing 9% year-over-year in H1 2026. That’s down somewhat from a 74% peak in 2022, mostly due to Chinese premium brands (Huawei, Xiaomi, Oppo) gaining ground with local Chinese consumers.
Profit share: 49%
Even more striking — Apple ships about 23% of all smartphones sold globally but captures roughly 49% of all industry profit. That’s the real story of Apple’s smartphone dominance: it doesn’t need to win on raw unit volume, because it owns nearly half the profit pool in an industry where most competitors are fighting over thin margins on low-cost devices. 20-25% of units globally, but 65% of the premium tier and 49% of industry profit, which is arguably the more meaningful number for understanding Apple’s actual market power.
Longer-term view
Bloomberg’s Mark Gurman has floated a much bigger thesis — that the Duo could do for foldables what the original iPhone did for touchscreens, potentially pushing foldables toward most phone sales within a decade as competition and scale bring costs down. That’s a notably more bullish take than the “under 3% of sales through 2026” consensus most other analysts are working with.
Being the Innovator is not the Goal
If innovation means inventing the category, no, Apple is consistently late, often by years. If innovation means defining what the category becomes — arguably yes, repeatedly. The common thread is that Apple tends to let others prove a market exists and work out the early technical kinks, then enters with tighter integration of hardware, software, and ecosystem, and a design/UX bar that competitors then must match. That’s a different skill than “first,” Palm, BlackBerry, and the original tablet makers all had real products and real markets and still lost those categories once Apple entered.
Fast Follower
The more precise term industry analysts use is “fast follower” or sometimes “second but better” — Apple rarely takes the invention risk, but it takes the much larger execution and timing risk of betting that a market is ready to go mainstream, then spending the resources to make the experience good enough that it becomes the default.
Ready to Make Price Irrelevant?
Apple shows that a remarkable customer experience can be your strongest competitive advantage. Is your business giving customers a reason to choose you beyond price? Contact The DiJulius Group for a complimentary call to explore how we can help you build a world-class customer experience that strengthens loyalty and makes price irrelevant.